

Financial independence is not a single savings target. The amount you need depends on the life you want to fund, the income you can reliably earn, and how much uncertainty you are prepared to manage. Lean FIRE and Fat FIRE describe two different approaches: one prioritizes reaching financial independence with comparatively modest spending, while the other aims to support a more expensive lifestyle.
Neither approach guarantees a particular retirement date or outcome. Both depend on assumptions about spending, investment returns, taxes, health, housing, and how long your assets must last. Understanding those assumptions can help you compare the approaches without treating a popular label or savings formula as a personal financial plan.
What Lean FIRE and Fat FIRE Mean
FIRE stands for financial independence, retire early. It generally describes building enough assets to cover living costs without depending on a full-time job. The terms Lean FIRE and Fat FIRE are informal labels, not standardized financial or tax categories. There is no universal income or portfolio threshold that separates them.
Lean FIRE
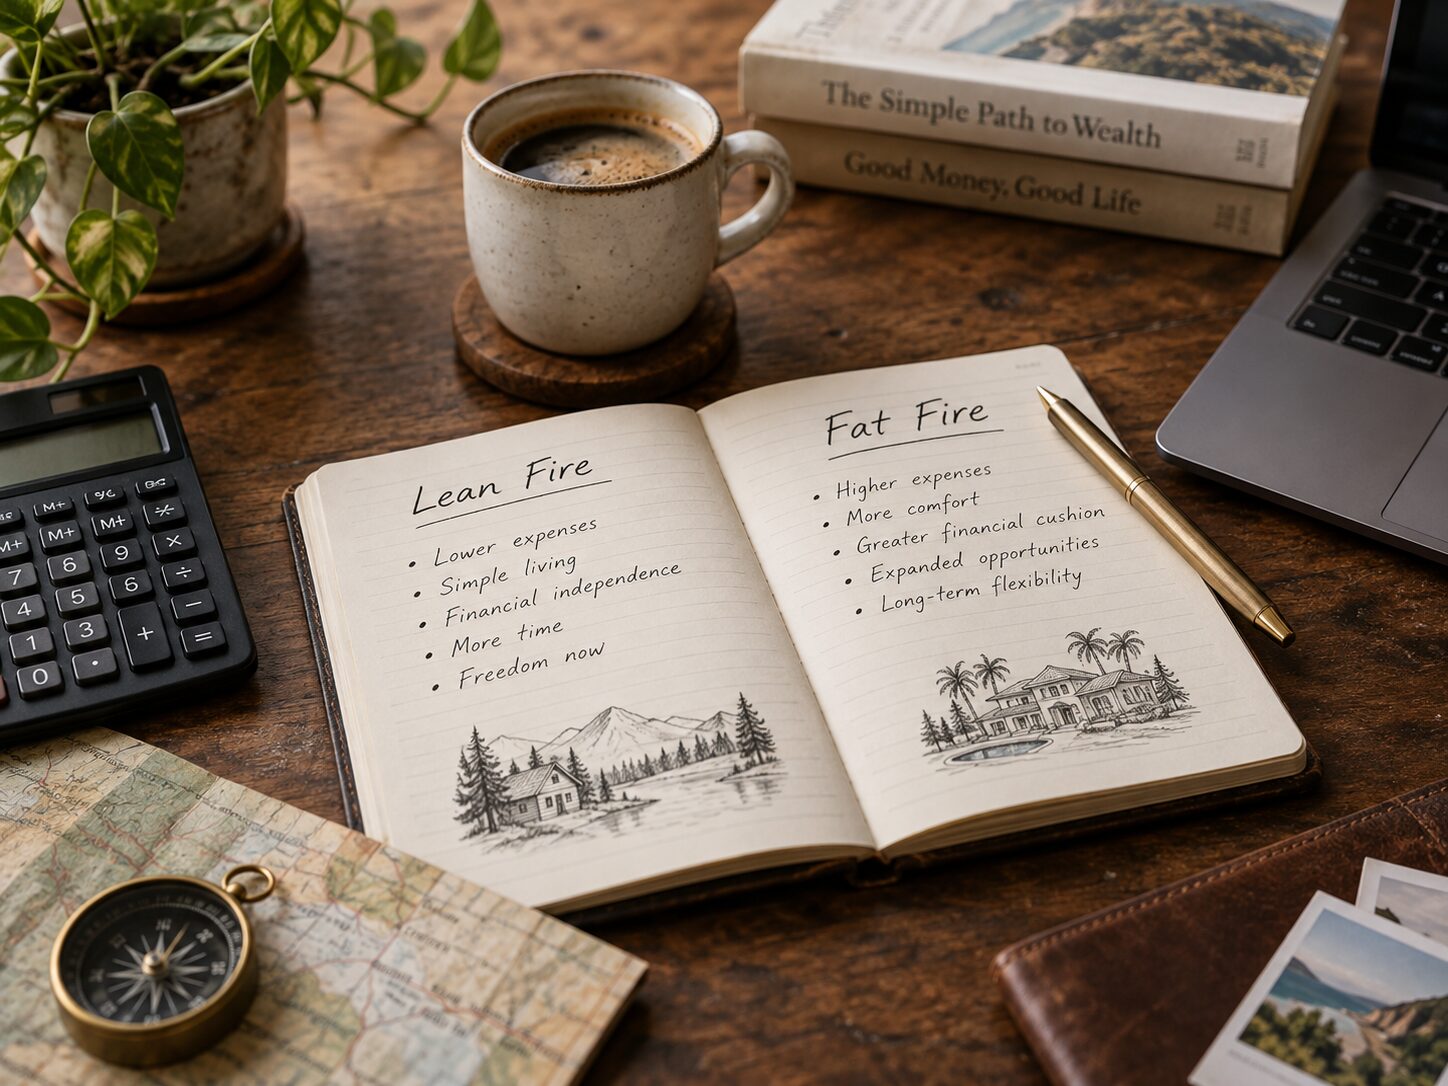
Lean FIRE means pursuing financial independence with a relatively low annual spending plan. Someone following this approach may expect to keep housing, transportation, food, and discretionary costs low. A smaller budget can mean a smaller portfolio target, which may make independence possible sooner if income and investment growth are sufficient.
The trade-off is that the plan may have less room for unexpected costs or changes in circumstances. A budget that works while healthy, employed part-time, or living in an affordable area may not work after a move, a medical expense, or a family change. Lean FIRE is most useful as a spending-based description, not as a promise that a particular dollar amount will be enough for everyone.
Fat FIRE
Fat FIRE means aiming for financial independence with a comparatively higher spending level. The plan may include more travel, a larger home, paid services, generous support for family, or a larger cushion for discretionary expenses. Because the desired spending is higher, the portfolio or other dependable income generally needs to be higher too.
A higher target can take longer to reach and may require a high savings rate, strong earnings, business income, or many years of investing. Fat FIRE does not automatically mean that a plan is secure: expensive habits, taxes, poor investment outcomes, or underestimated costs can still undermine it.
How the Spending Target Shapes the Portfolio
A common starting point is to estimate the annual amount that investments would need to support. One widely discussed heuristic is to divide annual portfolio withdrawals by a chosen withdrawal rate. For example, the arithmetic for a hypothetical $40,000 annual withdrawal at 4% is $1 million; the arithmetic for $120,000 is $3 million. These are illustrations, not recommended targets. They do not account for taxes, fees, healthcare, other income, changing spending, or a household’s specific risks.
The 4% rule is often associated with historical U.S. stock-and-bond portfolio research. William Bengen’s 1994 paper, “Determining Withdrawal Rates Using Historical Data,” examined historical returns and inflation-adjusted withdrawals. Cooley, Hubbard, and Walz’s 1998 paper, “Retirement Savings: Choosing a Withdrawal Rate That Is Sustainable,” examined related historical portfolio scenarios. Such research can inform discussion, but historical results do not guarantee future performance. Results depend on the period studied, asset mix, fees, inflation, taxes, and withdrawal behavior.
Early retirees may need their portfolios to last longer than the traditional retirement periods used in some research. A fixed withdrawal percentage may also be unsuitable when markets fall early in retirement, when spending is flexible, or when a large share of expenses is essential. Consider modeling several scenarios rather than treating one percentage as a rule.
Practical Steps to Compare the Two
1. Build a realistic spending baseline
Review at least a year of household spending where records are available. Separate essential expenses from discretionary ones, and include irregular costs such as repairs, insurance renewals, travel, taxes, and replacement of vehicles or appliances. If you are budgeting as a household, make sure both partners agree on the assumptions.
Model more than one future. Housing may change, dependents may need support, and health or care costs can shift. For Lean FIRE, test whether the lower budget still includes a practical reserve for these events. For Fat FIRE, check whether the higher target reflects durable priorities or spending estimates that might change.
2. Account for debt and emergency savings
List debts, interest rates, minimum payments, and payoff dates. Paying down high-interest debt can reduce financial pressure and interest costs, though the best choice between repayment and investing depends on rates, taxes, employer benefits, liquidity needs, and personal circumstances. Keep required payments current and avoid using retirement projections as a substitute for a workable payoff plan.
An emergency fund is separate from a long-term investment portfolio. It can help cover job loss, urgent repairs, or other near-term needs without forcing you to sell investments during a downturn. The appropriate reserve depends on income stability, household obligations, insurance, and access to other funds. A lean spending plan should not rely on having no emergencies.
3. Estimate taxes and accessible assets
Distinguish account balances from money you can spend after tax and any applicable withdrawal restrictions. Taxable brokerage accounts, workplace retirement plans, and individual retirement accounts can have different rules. Early access to some retirement accounts may involve taxes or penalties, subject to exceptions and account-specific rules.
Tax optimization can include using available tax-advantaged accounts, understanding asset location, and planning the timing and source of withdrawals. The right approach depends on jurisdiction, income, account type, and future tax law. Do not assume that a large retirement-account balance is immediately available at its full stated value.
4. Choose an investment approach you can maintain
Broad, diversified index funds are one possible way to invest for long-term growth. They can provide exposure to many securities at comparatively low cost, but they still carry market risk and can lose value. Diversification does not prevent losses, and an index fund is not automatically appropriate for every investor.
Set an asset allocation that reflects your time horizon, ability to tolerate losses, and need for reliable near-term spending. Revisit it periodically rather than reacting to every market move. Account fees, fund expenses, taxes, and the consequences of selling during a downturn all affect outcomes.
5. Test income beyond the portfolio
Some households plan to earn income through part-time work, consulting, a side hustle, rental property, or a small business. This can reduce the amount a portfolio must provide, but income may be irregular and can require substantial time, startup capital, maintenance, or insurance. Rental income, for example, is not automatically passive: vacancies, repairs, management, taxes, and financing costs matter.
Include only income that is plausible and reasonably modeled. A side hustle that depends on your labor may be a valuable part of a transition plan, but it is not the same as guaranteed investment income. If projected income stops, the plan should still have a clear response.
6. Review the plan under unfavorable conditions
Stress-test a plan for weak investment returns early in retirement, higher inflation, a prolonged period without earned income, major repairs, and changes in health or family obligations. Consider how you would respond: reduce discretionary spending, work temporarily, delay retirement, move, or draw from a different source of funds. A plan is more credible when it identifies adjustments in advance.
Credit score optimization can support borrowing options and may affect the terms offered by lenders, but a higher score does not substitute for an affordable budget. Pay bills on time, manage credit balances, review credit reports for errors, and borrow only when repayment fits the plan. Credit scores are not a measure of financial independence.
Neutral Pros and Cons
Lean FIRE: potential advantages
- A lower spending target can reduce the portfolio needed to support the plan.
- Modest expenses may make it easier to increase savings and build flexibility earlier.
- Simple, low-cost living can suit people whose priorities do not require high consumption.
Lean FIRE: potential disadvantages
- A narrow budget can be vulnerable to inflation, emergencies, or changes in housing and health needs.
- There may be less room for travel, family support, paid care, or other goals that emerge later.
- Maintaining a very low budget may depend on location or circumstances that cannot be assumed to remain constant.
Fat FIRE: potential advantages
- A larger spending allowance can provide more choice and room for discretionary goals.
- A broader cushion may make some unexpected costs easier to absorb, if the assets and plan are sufficient.
- Higher spending assumptions can make lifestyle trade-offs more explicit before leaving work.
Fat FIRE: potential disadvantages
- A larger target may require more time, higher income, or a greater exposure to investment risk.
- Higher ongoing costs can make a portfolio more sensitive to poor returns or underestimated inflation.
- More assets do not eliminate taxes, health costs, market losses, or uncertainty about future needs.
Limitations and Choosing a Direction
These labels can oversimplify different lives. A low-spending household may have expensive health needs, while a higher-spending household may have dependable pension income or other resources. A location change can alter housing and tax costs, but it can also affect access to family, care, and employment. There is no spending level that is inherently responsible or irresponsible without context.
Instead of choosing a label first, compare scenarios. Estimate essential and preferred spending, identify reliable income, account for taxes and debt, and calculate how much must come from investments. Then test whether the plan can adapt if returns or expenses differ from expectations. If the preferred lifestyle is not yet fundable, the comparison can reveal which factors are adjustable: retirement date, savings rate, spending, work income, location, or risk assumptions.
Budgeting strategies can help identify the gap between current spending and the chosen target. Increasing earnings through a side hustle or career change may help, but so can reducing recurring costs or paying down expensive debt. Real estate investing may diversify sources of income for some people, but it concentrates capital and brings operational and market risks. No single tactic guarantees financial independence.
Concise Q&A
Is Lean FIRE always faster than Fat FIRE?
Not necessarily. A lower spending target can reduce the required assets, but the timeline also depends on income, savings, returns, debt, taxes, and unexpected costs.
Is the 4% rule a safe withdrawal rate for early retirement?
It is a historical heuristic, not a guarantee or individualized recommendation. A longer retirement horizon, different market conditions, taxes, fees, and spending flexibility can change the result.
Can passive income replace a portfolio?
It may contribute to expenses, but income from investments, property, or businesses can fluctuate and involve risk, costs, and work. Evaluate net income and what happens if it falls.
Which approach is better?
Neither is universally better. The suitable target depends on the life you want, the resources available, and your ability to manage uncertainty without relying on unrealistic assumptions.
Sources and Method
This comparison uses Lean FIRE and Fat FIRE as informal spending-style labels, not fixed technical definitions. The portfolio discussion is grounded in the historical withdrawal-rate research of William Bengen (1994) and Cooley, Hubbard, and Walz (1998), while emphasizing that past results do not establish future outcomes. Tax and account rules should be checked against current guidance from the relevant tax authority and account provider.
Informational disclaimer: This article is educational and is not individualized investment, tax, legal, or financial advice. Investment values can fall, and withdrawal strategies can fail to meet future needs. Consult qualified professionals about decisions that depend on your circumstances and applicable laws.