

Understanding why retirement planning is important in India starts with a practical question: how will you pay for everyday life when regular earnings stop? Retirement planning connects the money you save today with the income you will need later, while accounting for inflation, emergencies and your preferred lifestyle. The Securities and Exchange Board of India (SEBI) encourages early saving, suitable insurance and diversified investments as part of this preparation. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters-planforearlyretire.html))
Begin with your own circumstances: household spending, existing savings, debts, dependants and the age at which you would like work to become optional. Use the following framework to turn those details into a plan you can review and adjust.
What Is Retirement Planning?
Retirement planning is the process of estimating your future living costs, building financial resources during your working years and deciding how those resources will support you after retirement. It involves assumptions about retirement age, longevity, inflation, investment returns and existing assets. The National Institute of Securities Markets (NISM) includes these inputs in its retirement planning calculator. ([nism.ac.in](https://www.nism.ac.in/financial-calculators/retirement-planning/))
For this guide, financial independence means being able to meet your planned expenses without depending on continued employment. Treat retirement planning as a household project: decide what you want to fund, identify what is already available and calculate what remains to be built.
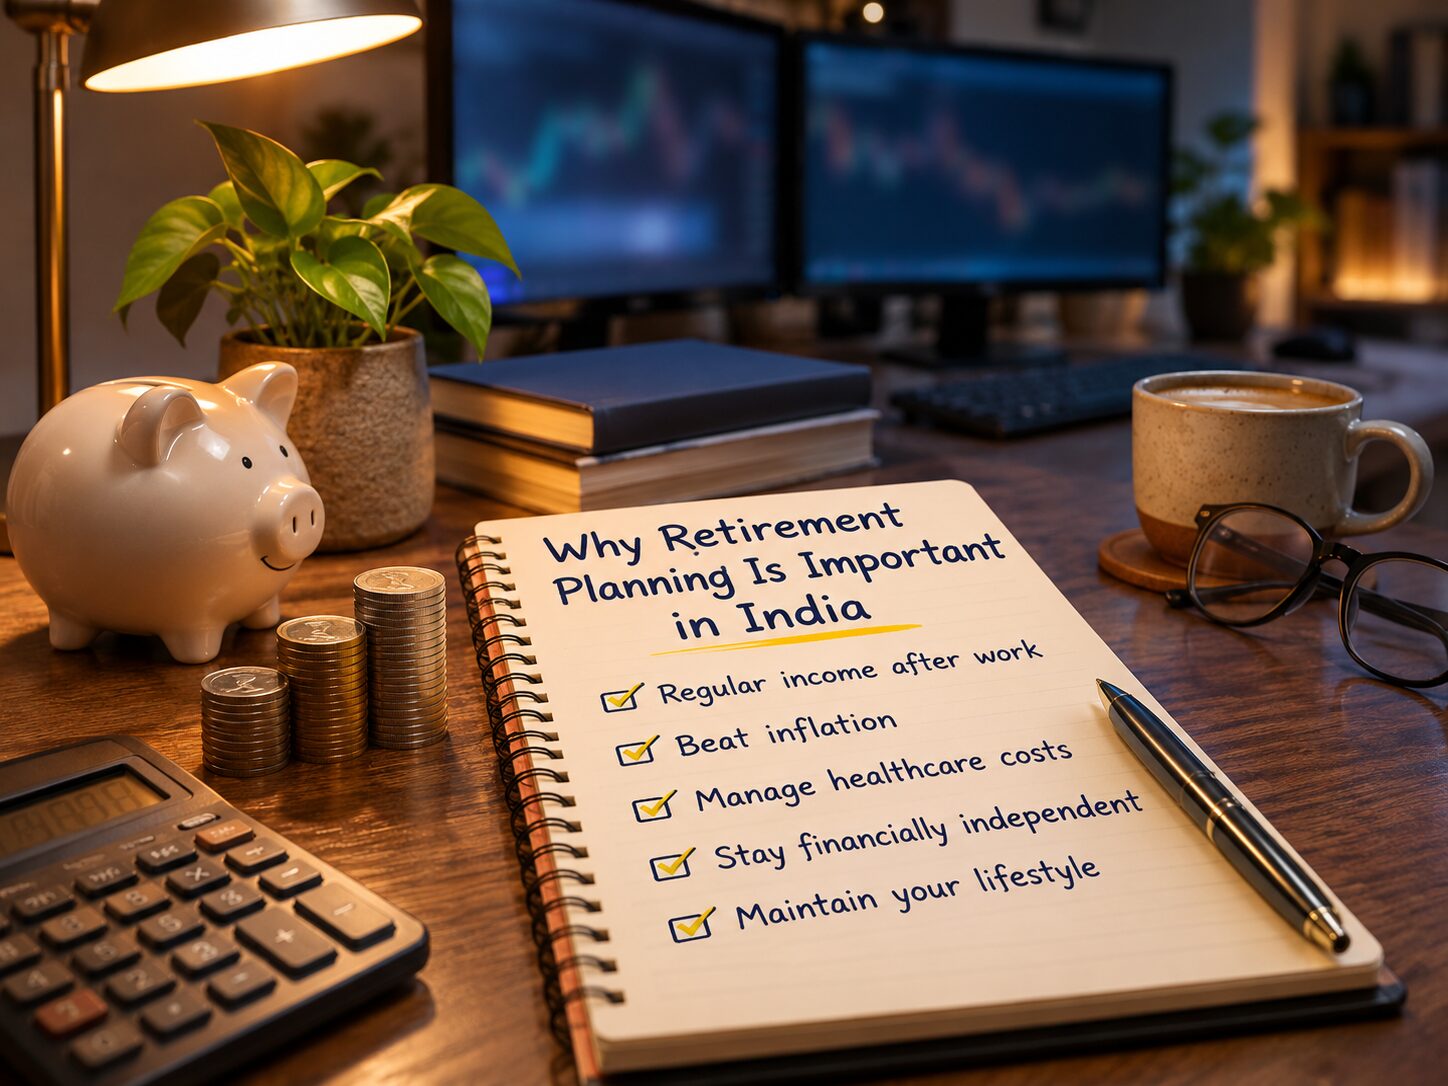
Why Retirement Planning Is Important in India
Inflation changes what your savings can buy
A retirement target based only on today’s prices can underestimate future spending. Inflation reduces purchasing power, so maintaining a similar lifestyle may require a larger rupee amount later. The Pension Fund Regulatory and Development Authority (PFRDA) explicitly includes inflation in its retirement education material. ([pfrda.org.in](https://www.pfrda.org.in/documents/33652/212539/English%2B-%2BRetirement%2BEducation%2Band%2Bawareness%2Bprogram.pdf))
Estimate food, housing, transport and healthcare separately. Then test more than one inflation assumption instead of relying on a single forecast. Give particular attention to expenses that would be difficult to reduce.
Your money must support an uncertain retirement period
You cannot know exactly how long retirement will last. That makes longevity an essential planning assumption, alongside the age at which earnings end. NISM’s calculator distinguishes retirement age from the age through which retirement expenses must be funded. ([nism.ac.in](https://www.nism.ac.in/financial-calculators/retirement-planning/))
For a couple, prepare a household plan that considers the surviving partner’s needs. Ask whether that person could manage the accounts, access necessary documents and cover essential spending independently.
A retirement account does not automatically mean adequate income
PFRDA describes the National Pension System (NPS) as a defined contribution system with market-linked returns. Having an account therefore does not, by itself, establish that your eventual retirement resources will cover your spending. Contributions, investment outcomes and your requirements still matter. ([pfrda.org.in](https://www.pfrda.org.in/en/schemes/national-pension-system/about-nps))
List each expected benefit separately. Record its estimated amount, availability date and supporting document. Keep uncertain family assistance, possible inheritances and hoped-for business sales outside your essential-income calculation.
Starting earlier creates more time to prepare
SEBI notes that saving early gives investments more time to compound. It also recommends preparing for emergencies and choosing investments with retirement goals in mind. Starting early creates a longer preparation period, although investment growth remains uncertain. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters-planforearlyretire.html))
If you are starting later, focus on decisions still within your control: contributions, expenses, retirement timing and the lifestyle you intend to fund. Avoid making a higher assumed return the only solution to a shortfall.
Practical Steps to Build Your Retirement Plan
1. Define your retirement lifestyle and budget
SEBI’s financial education material identifies budgeting, saving and goal setting as connected parts of personal finance. Use those ideas to prepare a retirement budget rather than selecting an investment product first. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters.html))
Build three spending lists:
- Essentials: housing, groceries, utilities, transport, insurance and routine healthcare.
- Flexible expenses: travel, entertainment, gifts and hobbies.
- Occasional expenses: repairs, replacement appliances and major family commitments.
Review actual account statements when completing these lists. Remove work-related spending you expect to stop, but add retirement activities you truly want to afford. Discuss family support commitments explicitly rather than leaving them as an unpriced expectation.
2. Identify your income gap
For an initial snapshot, subtract dependable retirement income from estimated retirement spending, using amounts expressed in the same year’s purchasing power.
Illustrative example: Suppose a hypothetical household budgets ₹50,000 a month and expects dependable income of ₹20,000 a month, both in today’s rupees. Its starting gap is ₹30,000 monthly, or ₹3.6 lakh annually. These are invented planning inputs, not typical Indian household figures or a recommended spending level.
This subtraction is only a starting point. A full projection must account for when retirement begins, how spending changes, how long withdrawals continue and what resources are already available. NISM’s calculator illustrates how these inputs interact; its assumptions should be reviewed rather than accepted automatically. ([nism.ac.in](https://www.nism.ac.in/financial-calculators/retirement-planning/))
3. Connect budgeting strategies to contributions
Create a specific retirement contribution within your household budget. SEBI defines saving as setting aside income for future goals and budgeting as planning how to save and spend effectively. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters.html))
Try a practical monthly routine: record income, reserve money for essentials and debt payments, fund planned savings, then assign the remainder to discretionary spending. Choose an initial contribution you can maintain without borrowing for ordinary expenses.
For irregular earnings, consider a modest baseline contribution plus an additional amount after stronger months. Review the arrangement after income changes, rather than treating the original contribution as permanent.
4. Prepare an emergency fund and review insurance
SEBI’s retirement guidance recommends savings for unexpected expenses and adequate insurance for unforeseen events. The Reserve Bank of India (RBI) also advises keeping some savings liquid so that money is available when needed. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters-planforearlyretire.html))
Set your emergency reserve according to your household’s circumstances. Consider income stability, dependants, essential bills and possible interruptions to work. Give this reserve a separate label in your records so that it is not also counted toward retirement.
When reviewing insurance, ask the insurer to explain exclusions, renewal conditions and expenses you would still pay yourself. Include those potential payments in your household stress test.
5. Coordinate debt payoff and credit management
RBI’s financial awareness guidance recommends borrowing within your repayment capacity, paying instalments on time and seeking corrections to inaccurate credit information. These are useful foundations for credit score optimization. ([rbi.org.in](https://www.rbi.org.in/commonperson/images/FAME202426022024.pdf))
Prepare a debt inventory showing each balance, interest rate, minimum payment and any prepayment charge. Compare the cost of carrying each debt with your other priorities before allocating surplus cash.
Consider directing extra repayments toward the most expensive debt while maintaining required payments elsewhere and preserving emergency liquidity. Do not take additional loans merely to pursue a higher credit score. Make debt reduction serve your retirement budget.
6. Choose investments by purpose and risk
Index fund investing can provide exposure to the securities in a chosen index. SEBI explains that index funds aim to track that index and generally have lower management costs than actively managed funds. Their performance still reflects the underlying market and fund expenses. ([investor.sebi.gov.in](https://investor.sebi.gov.in/index_mutual_fund.html))
A broadly diversified index fund may suit part of a long-term portfolio, but an index label alone does not establish suitability. Compare the benchmark, holdings, costs and tracking behaviour. Use SEBI’s Riskometer information to help assess a mutual fund’s stated risk level. ([investor.sebi.gov.in](https://investor.sebi.gov.in/index_mutual_fund.html))
NPS is another retirement vehicle to evaluate. PFRDA describes it as portable across employers and locations, with investment choices and market-linked returns. Before contributing, review the applicable access, exit and payout conditions against your own timeline. ([pfrda.org.in](https://www.pfrda.org.in/en/schemes/national-pension-system/about-nps))
For every proposed investment, write down its job: emergency access, near-term spending or longer-term growth. Then ask whether its potential losses and access conditions are consistent with that job.
7. Evaluate passive income and property conservatively
Use a cash-flow test when considering passive income or real estate investing. For a proposed rental property, estimate money remaining after loan payments, maintenance, taxes, insurance, management and periods without a tenant. Stress-test a major repair and an extended vacancy before including rent in essential retirement income.
Also decide what the property is intended to do: provide housing, generate rent or supply sale proceeds. In your projection, avoid counting the same property as both a future sale asset and a continuing source of rental income after that sale.
Apply a similar test to side hustles. Record revenue after expenses and taxes, then ask whether the activity would still be practical if your health, energy or availability changed. Treat untested income as an optional scenario.
8. Check taxes and establish a review routine
Tax optimization requires checking your applicable regime, contribution type and financial year. The Income Tax Department’s guidance distinguishes deductions available under different regimes, including the treatment of pension contributions. Do not assume that every retirement contribution qualifies for the same benefit. ([incometax.gov.in](https://www.incometax.gov.in/iec/foportal/help/individual/return-applicable-1))
Compare investments after considering fees, taxes, access and risk. Verify the rules applicable when you contribute and when you withdraw, using current official guidance.
Set an annual review date. Update spending, balances, contributions, debts, insurance and retirement timing. Add an earlier review after a major income change, marriage, bereavement or new care responsibility.
Pros, Cons and Trade-Offs
Retirement planning involves choices between competing needs. Use the following comparisons to make those choices explicit:
- Saving more today: allocates more money to future needs, but leaves less available for current spending. Choose a contribution that fits a workable household budget.
- Using index funds: can offer transparent benchmark exposure and relatively low costs, but does not remove market risk or guarantee returns. ([investor.sebi.gov.in](https://investor.sebi.gov.in/index_mutual_fund.html))
- Using debt mutual funds: provides exposure to debt securities, but involves risks including interest-rate changes and issuer default. Do not equate the word ‘debt’ with guaranteed capital protection. ([amfiindia.com](https://www.amfiindia.com/investor/knowledge-center-info?zoneName=riskInMutualFunds))
- Choosing NPS: offers a dedicated retirement structure and portability, but requires evaluating market exposure and applicable exit conditions. ([pfrda.org.in](https://www.pfrda.org.in/en/schemes/national-pension-system/about-nps))
- Planning to work longer: gives your projection additional earning years, but should be tested alongside a scenario in which continued work is unavailable.
Limitations and How to Test Your Plan
A projection is conditional, not a promise. Investment values can fall, and mutual funds do not provide assured returns simply because they are held for retirement. The Association of Mutual Funds in India (AMFI) explains that both equity and debt investments carry risks. ([amfiindia.com](https://www.amfiindia.com/investor/knowledge-center-info?zoneName=riskInMutualFunds))
Use a comparison method with consistent inputs. Keep the same household budget and retirement date across your initial scenarios, then change one assumption at a time: inflation, returns, retirement duration or supplementary income. Finally, combine several unfavourable assumptions to see which expenses become difficult to fund.
Record your response to a shortfall before choosing products. Possible adjustments include higher contributions, lower discretionary spending, a different retirement date or revised housing plans. Keep the emergency reserve separate and avoid counting savings already committed to another goal.
Concise Q&A
When should I start retirement planning?
Start when you can begin setting aside money consistently. SEBI encourages early saving because it provides more time for compounding. Review your contribution as your circumstances improve. ([investor.sebi.gov.in](https://investor.sebi.gov.in/moneymatters-planforearlyretire.html))
How much money will I need?
Estimate it from your spending, retirement age, expected retirement duration, existing resources and investment assumptions. These are central inputs in NISM’s retirement calculator; a universal rupee target cannot capture them all. ([nism.ac.in](https://www.nism.ac.in/financial-calculators/retirement-planning/))
Are index funds sufficient on their own?
Do not assume so. An index fund follows its chosen market, and suitability depends on the risk you can bear. Evaluate its role alongside your spending needs and other resources. ([investor.sebi.gov.in](https://investor.sebi.gov.in/index_mutual_fund.html))
Can I begin with a small contribution?
Choose an affordable starting amount, include it in your budget and set a date to reassess it. Treat that amount as the beginning of the process, not evidence that the entire retirement goal is funded.
Informational disclaimer: This article provides general financial education, not personalized investment, tax or legal advice. Examples are illustrative. Verify current product rules and tax treatment, and seek appropriately qualified advice for decisions involving your circumstances.