

The cash envelope system is a budgeting method that assigns money to specific spending categories before you spend it. Each category has its own envelope, whether physical or digital, and you stop spending from that category when its balance reaches zero. The method is designed to make discretionary spending visible and limited, which can help people who find it difficult to follow a traditional spreadsheet or banking-app budget.
This guide explains cash envelope system how it works, how to set one up, where it can help, and where it has limitations. It also places the method alongside other financial priorities, including debt payoff, emergency savings, investing, retirement planning, credit management, tax planning, side hustles, and real estate investing.
What Is the Cash Envelope System?
The cash envelope system is a zero-based or category-based budgeting approach. At the beginning of a budgeting period, you decide how much money is available for expenses such as groceries, dining out, transportation, entertainment, clothing, and household supplies. You then assign a spending limit to each category.
In the traditional version, you withdraw cash and place the amounts in labeled envelopes. If the grocery envelope contains $300, for example, that is the amount available for groceries during the selected period. When the envelope is empty, you either stop buying in that category, move money from another category, or consciously revise the plan.
A digital version uses separate bank subaccounts, prepaid budgeting tools, or an app that tracks virtual envelopes. The underlying principle is the same: money is assigned a purpose before it is spent.
How the Cash Envelope System Works
1. Calculate income available for the period
Start with take-home income rather than gross pay. Include regular wages and reasonably predictable income, but treat irregular earnings conservatively. If you receive money from a side hustle, commission, or freelance work, consider budgeting only the amount you can reasonably expect after business costs and taxes.
List the dates and amounts of expected income. A monthly plan may work well for salaried workers, while people paid weekly, biweekly, or irregularly may need a paycheck-based plan. The timing matters because an envelope system cannot solve a cash-flow gap by itself.
2. Separate fixed, variable, and irregular expenses
Fixed expenses usually include rent or a mortgage, insurance, loan payments, and required subscriptions. Variable expenses include groceries, fuel, dining, entertainment, and personal spending. Irregular expenses may include annual insurance premiums, school costs, vehicle repairs, gifts, or property taxes.
Cash envelopes are usually most useful for variable expenses that are easy to overspend. Fixed bills can remain in a checking account and be paid automatically if that arrangement is safe and affordable. Irregular expenses may need sinking funds, which are separate savings categories built gradually for known future costs.
3. Review recent spending
Examine several recent months of bank and card transactions. Group purchases by purpose rather than by merchant. A supermarket purchase may include groceries, household products, and personal-care items, so choose category definitions that are practical enough to use consistently.
Do not set limits only because they look appealing. A category that is too low may force repeated transfers and make the system frustrating. A realistic starting point can be adjusted after you observe actual spending.
4. Assign every dollar a job
After covering essential bills, assign available money to variable spending, debt payments, savings, and other priorities. This is sometimes called giving every dollar a job. The goal is not necessarily to spend all money immediately; savings and debt reduction are also valid assignments.
A basic order might be current bills, a starter emergency reserve, minimum debt payments, necessary spending, additional high-interest debt payments, and longer-term goals. The right sequence depends on income stability, interest rates, employer benefits, family responsibilities, and the terms of your debts.
5. Fund the envelopes
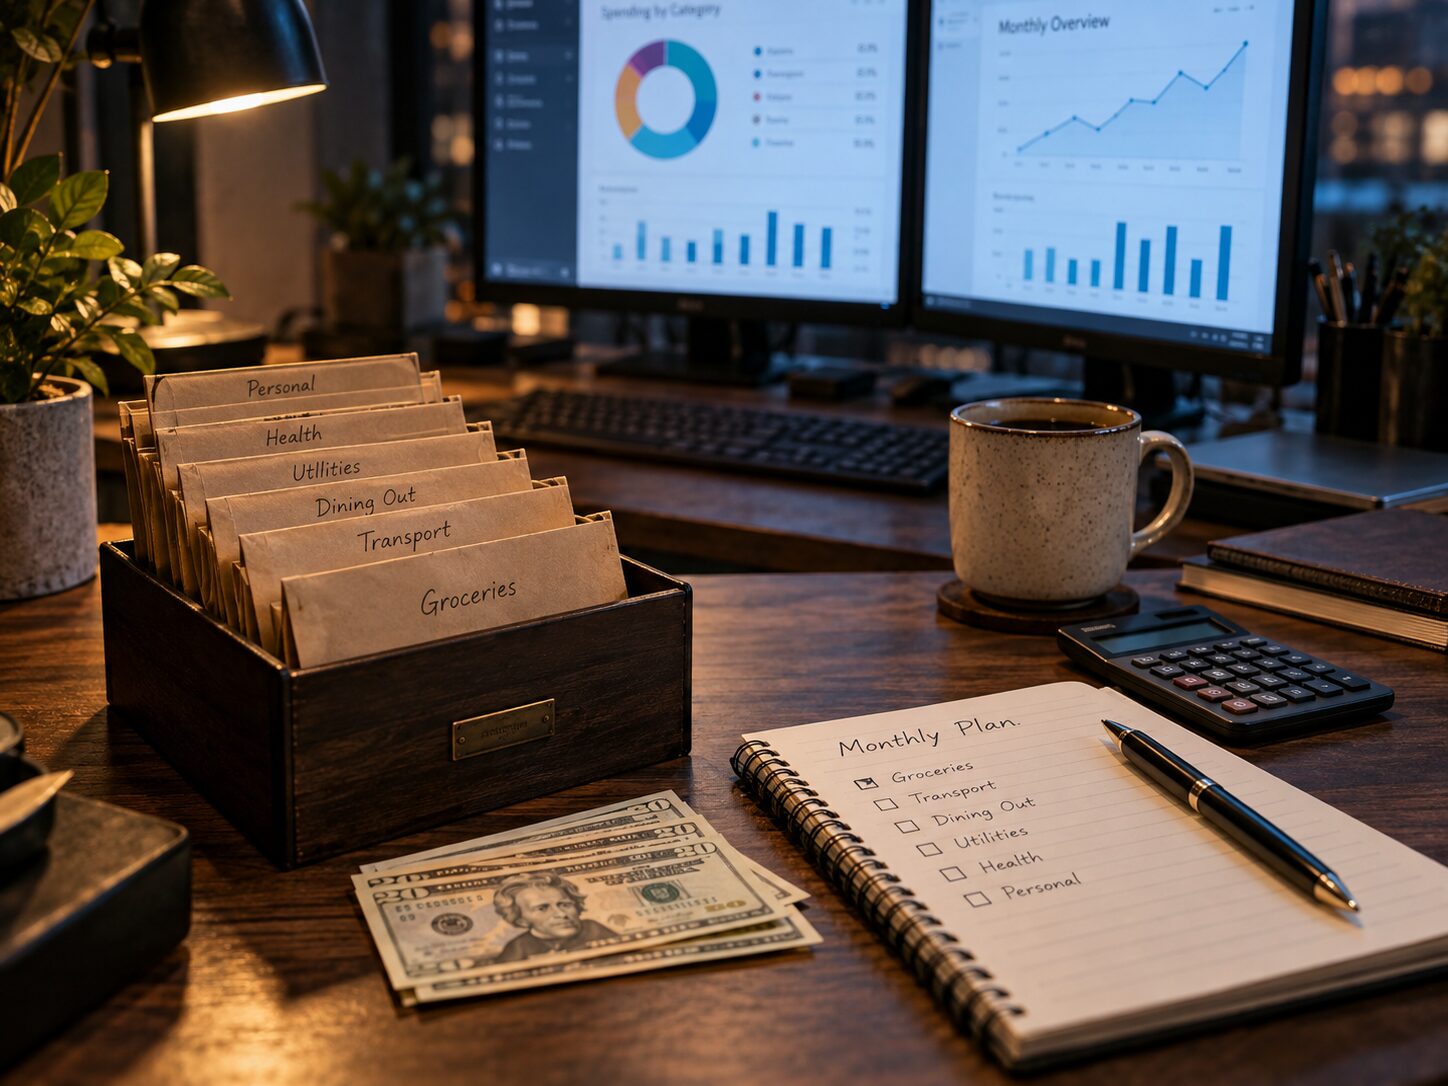
For a physical system, withdraw only the amount you have assigned to cash categories. Label each envelope clearly. You might use categories such as groceries, restaurants, transportation, household items, clothing, entertainment, and personal spending.
For a digital system, keep bill money and savings separate from spending money when possible. Some banks allow labeled subaccounts, while budgeting apps may let you create virtual categories. Confirm whether transfers are immediate, whether there are fees, and whether funds remain insured under the account structure. The Federal Deposit Insurance Corporation, or FDIC, provides information about deposit insurance and account ownership at FDIC-insured banks.
6. Record purchases as they happen
Subtract each purchase from the relevant envelope. If one shopping trip includes several categories, divide the purchase while you are still able to remember the amounts. In a physical system, keep receipts or write the transaction on the envelope. In a digital system, update the category promptly.
The system works through awareness. If you do not record spending or review balances, the envelopes become labels rather than limits.
7. Handle overspending deliberately
If one envelope runs out, avoid silently using a credit card or pulling money from an unknown source. Instead, choose a specific response: stop spending in that category, move money from a lower-priority category, use a designated buffer, or revise the next period’s allocation.
Transfers should be recorded. Otherwise, a category may appear affordable while another category is quietly depleted. Repeated overspending can indicate that the limit is unrealistic, the category is too broad, or an irregular expense needs its own sinking fund.
A Practical Setup Example
Suppose a household receives regular take-home income and has already identified money for rent, utilities, insurance, minimum debt payments, and retirement contributions. It could create spending envelopes for groceries, fuel, dining out, household supplies, personal spending, and entertainment. It could also create non-spending savings categories for vehicle maintenance, annual insurance, medical costs, and an emergency fund.
At the start of the period, the household funds each category based on its plan. A grocery purchase reduces the grocery balance, while a restaurant purchase reduces the dining balance. If dining money is exhausted, the household must either wait, transfer money from another category, or make a conscious decision to change the budget. This friction is intentional: it makes trade-offs visible before spending becomes debt.
The example does not establish a recommended allocation. Housing costs, family size, location, health needs, debt obligations, and income volatility vary substantially. Use transaction history and personal priorities rather than copying another person’s percentages.
Physical Cash Versus Digital Envelopes
Physical cash
Physical cash creates a strong visual and tactile limit. It can be useful for categories where card payments lead to frequent impulse purchases. However, carrying cash can be inconvenient, and lost or stolen cash may be difficult to recover. Cash also may not work for online payments, recurring charges, deposits, or merchants that do not accept it.
Keep only the amount needed for current spending with you, store remaining cash securely, and avoid writing sensitive account information on an envelope. The method should not put you at unnecessary risk when traveling or paying for essential services.
Digital envelopes
Digital categories are easier for online purchases and can preserve transaction records. They may also reduce the risk associated with carrying cash. Their disadvantages can include app fees, transfer delays, technical problems, account complexity, or the temptation to move money without reflecting on the trade-off.
Before using a financial app, review its privacy policy, security controls, withdrawal rules, and whether balances are held at an insured bank. Do not assume that an app or payment provider offers the same protections as a bank account.
Benefits of the Cash Envelope System
- It makes limits visible. A remaining balance is easier to understand than a single checking-account total that includes money reserved for bills.
- It can reduce discretionary overspending. Spending stops or requires a deliberate transfer when a category is empty.
- It supports intentional trade-offs. Moving money from entertainment to groceries makes the cost of a choice clear.
- It can help people who dislike complex software. A small number of labeled categories may be easier to maintain than a detailed financial dashboard.
- It can support debt payoff. Controlling flexible spending may free money for extra payments, especially on high-interest debt.
Drawbacks and Limitations
- It requires maintenance. Balances must be updated, and categories must be reviewed when circumstances change.
- It may not fit all expenses. Rent, utilities, taxes, insurance, online purchases, and automatic payments generally require a bank-account workflow.
- Cash creates security and convenience concerns. Lost or stolen money may not have the same protections as an electronic transaction.
- Irregular income can make funding difficult. A monthly envelope plan may be unreliable when income changes substantially.
- It does not increase income or eliminate debt automatically. A budget can reveal a shortfall, but the shortfall still requires spending changes, more income, creditor negotiation, or professional advice.
- It does not replace financial planning. The method does not by itself choose investments, optimize taxes, improve a credit report, or determine suitable insurance coverage.
The system is a tool, not a test of discipline. If cash envelopes create conflict, anxiety, or unsafe situations, a simpler digital budget or automated account structure may be more appropriate.
How It Relates to Other Financial Goals
Emergency fund
An emergency fund is money reserved for unplanned, necessary expenses or an income interruption. It should generally be kept in an accessible, low-risk account rather than mixed with everyday spending envelopes. The Consumer Financial Protection Bureau, or CFPB, discusses emergency savings as a way to prepare for financial shocks. The appropriate amount depends on job stability, household obligations, insurance, and access to other resources.
Debt payoff
Once minimum payments are covered, an envelope budget can identify money for additional debt payments. The debt avalanche method prioritizes the highest interest rate, while the debt snowball method prioritizes the smallest balance. Compare interest rates, fees, promotional terms, and behavioral fit before choosing. Keep required payments current because missed payments can harm credit history.
Credit score optimization
Cash budgeting does not directly raise a credit score. Credit scoring models generally consider factors such as payment history, amounts owed, account age, credit mix, and applications, although the exact treatment depends on the scoring model. Paying on time, reviewing credit reports for errors, and avoiding unnecessary applications are more directly relevant. You can obtain federally authorized free credit reports through AnnualCreditReport.com.
Index fund investing and retirement planning
After covering immediate needs and establishing a suitable cash reserve, some people direct recurring amounts toward workplace retirement plans, individual retirement accounts, or taxable investment accounts. Index funds seek to track a market index and still carry investment risk, including the possibility of losing principal. Investor.gov, operated by the U.S. Securities and Exchange Commission, provides educational material on diversification, mutual funds, exchange-traded funds, and fees.
An envelope system can reserve money for retirement contributions, but it cannot determine an appropriate asset allocation. Time horizon, risk tolerance, tax treatment, employer matching rules, and fees matter.
Side hustles and tax optimization
Income from freelance work, contract jobs, or online sales may involve expenses and tax obligations. Keep business and personal spending records separate where practical. The Internal Revenue Service provides guidance on self-employment income, estimated taxes, deductible business expenses, and recordkeeping. Tax planning should be based on current rules and, when circumstances are complex, advice from a qualified tax professional.
Real estate investing
A property purchase requires more than a down payment. Buyers may need reserves for closing costs, maintenance, insurance, taxes, vacancies, and changes in borrowing costs. A real-estate sinking fund can help distinguish a planned investment from money needed for everyday bills. Do not use an envelope balance as evidence that an investment is affordable without evaluating cash flow, debt, liquidity, and risk.
Q&A: Cash Envelope System How It Works
Is the cash envelope system only for people who overspend?
No. It can help anyone who wants clearer category limits, including households with stable spending. People who already use a successful digital budget may gain little from changing systems.
What categories should go in envelopes?
Start with flexible categories that frequently cause confusion or overspending, such as groceries, dining, entertainment, clothing, fuel, and personal spending. Keep the number manageable. Bills and long-term savings can remain in separate accounts or automated allocations.
What happens when an envelope has money left?
Choose a rule in advance. You might roll it into the next period, direct it to an emergency fund or sinking fund, apply it to debt, or use it for a planned goal. A consistent rule prevents leftover money from disappearing into untracked spending.
Can I use credit cards with this system?
Yes, but you must reserve the cash for each card purchase and record it immediately. Pay the statement balance from the matching envelope allocation. If card use causes overspending or balances to grow, a cash or debit-based approach may be safer.
How often should I review the budget?
Check balances whenever you spend and conduct a fuller review at the end of each budgeting period. Adjust for price changes, seasonal costs, income changes, and progress toward savings or debt goals.
Bottom Line
The cash envelope system works by assigning available money to clear spending categories and limiting each category to its funded balance. Its main strength is visibility: it turns an abstract budget into a set of concrete choices. Its main weaknesses are maintenance, limited flexibility, and the risks or inconvenience of physical cash.
Use it as one part of a broader plan. Pair category limits with an emergency fund, timely debt payments, appropriate retirement saving, careful credit management, and tax-aware recordkeeping. Compare the method with established consumer-finance guidance from the CFPB, FDIC, Investor.gov, and the IRS rather than relying on unverified claims or rigid universal percentages.
Informational disclaimer: This article is for general educational purposes and is not individualized financial, investment, tax, legal, or credit advice. Rules and account protections can change. Review official sources and consult a qualified professional before making decisions that materially affect your finances.